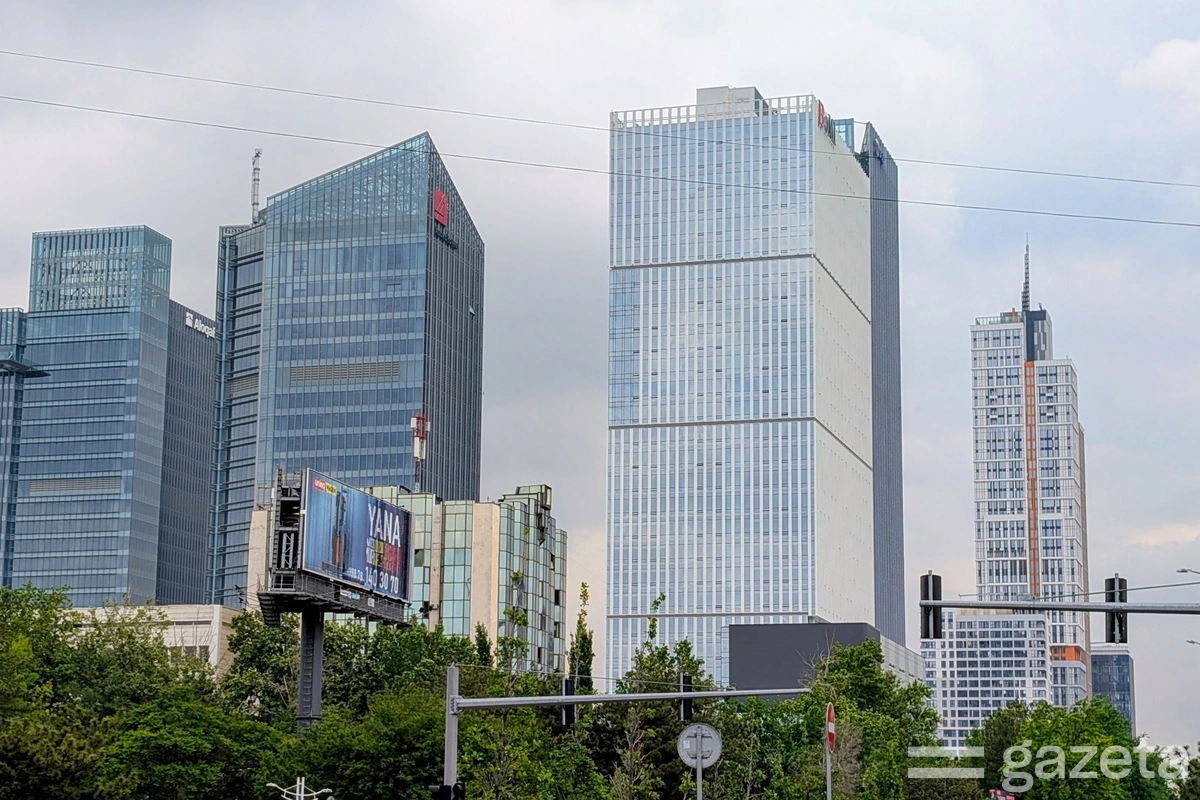
Photo: Shukhrat Latipov / Gazeta
Tashkent's Office Market Enters a More Mature Phase. What's Happening with Supply, Rates, and Demand – CMWP Uzbekistan Research
Over six years, the volume of office space available for rent in Tashkent has more than quadrupled. Now, supply growth is slowing down. CMWP Uzbekistan analysts believe the market is entering a more mature phase. This review of the company's research details the factors driving these changes.
In 2026, CMWP Uzbekistan updated its database of Tashkent office properties. It now includes 138 existing, under construction, and undergoing reconstruction business centers, including those previously not accounted for by the company – primarily Class B and C.
To more accurately interpret local market changes, experts have introduced the "Prime" category. In the company's new classification, this denotes Class A+ properties, encompassing the capital's key office buildings that meet the highest standards for engineering systems (including 4-pipe air conditioning and humidification), parking availability, and single-owner structures.
"The выделение of premium segment business centers allows for a more precise determination of the market's upper price range and enhances the comparability of properties within each class," the report states.
The total office stock in Tashkent also includes Built-to-Suit (BTS) properties – business centers constructed for a specific tenant. As these are not available on the open rental market, analysts do not include them when calculating market vacancy and average rental rates.
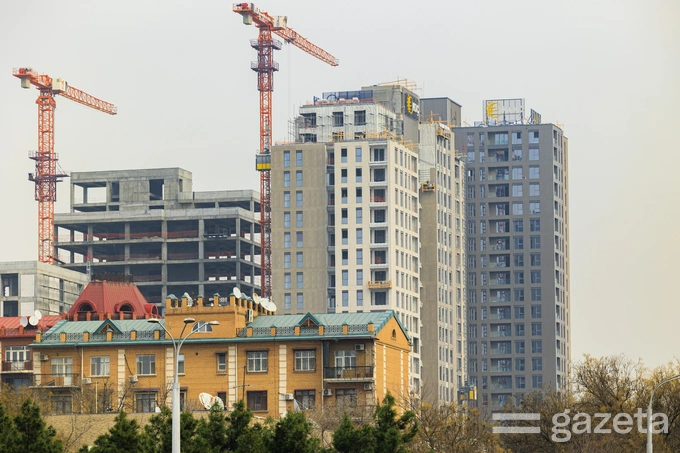
As of September 2026, the total Gross Leasable Area (GLA) is 1,074,946 sq. m, including 282,270 sq. m of BTS properties.
Since the beginning of 2026, the Summit and BoMI business centers, and Infinity Tower 2 (Classes A and Prime) have been commissioned, along with Sapphire and Chust (Class B). The combined area of these properties is 125,457 sq. m GBA and 85,389 sq. m GLA.
Analysts note that further market development will primarily be driven by the implementation of already announced projects.
"In the next four years, according to developer announcements, 13 more business centers are planned for commissioning: four Class A and nine Class B. The total volume of new supply, including the return of one property to the market after reconstruction, will exceed 112 thousand sq. m GLA – approximately 14% of the current leasable area. This indicates a slowdown in supply growth," the report states.
Within the existing supply structure, excluding BTS properties, Class B business centers are predominant. Their share in the total stock has grown from 43% in 2020 to 55% in 2026.
Prior to 2021, Class C business centers formed the basis of the office stock. However, by 2026, their share decreased from 57% to 21.4%.
The formation of a high-class office segment began in 2021 with the emergence of the first Class A business centers. In 2023, the first Prime category properties entered the market. By 2026, the combined share of Class A and Prime category properties reached 23.6%.
The vacancy rate in the existing office real estate market in 2026 is approximately 16.9%. This is slightly higher than the 2025 figure (~16%) but significantly lower than the 2024 level (25%). About half of all vacant space is in Prime category properties. The high concentration of vacant space in the Prime category is primarily due to the commissioning of the new Summit and BoMI business centers. In Classes A and B, approximately 23% of space is vacant.
Between 2023 and 2026, rates in Classes B and C have almost returned to their 2023 levels, indicating price stability in these segments. Currently, the average marketed rate in Classes B and C, including VAT and operating expenses, ranges from $23 to $31.
In contrast, Class A has seen a notable correction. After reaching a peak of $44 per sq. m in 2025, the rate has decreased to approximately $36. The report notes that this decrease is attributed not only to market correction but also to the separation of Prime properties into a distinct category, which influenced the average rate. CMWP Uzbekistan points out that the presence of office fit-out increases the final market rate by approximately 15-35% compared to the net rental rate.
Actual demand is characterized by a broad industry structure. The largest share is held by trade and distribution (25%), followed by IT companies (16%), consulting (15%), and the banking, finance, and investment sector (around 15%). Together, these sectors account for over 55% of demand, confirming the focus of business centers primarily on commercial and technologically advanced industries.
Healthcare, manufacturing, and the construction/development sector collectively represent a significant portion (around 5% each). Smaller shares are held by raw material and energy companies (4%) and government structures (about 3%).
CMWP Uzbekistan believes the market is transitioning to a more mature phase: the pace of new construction is slowing, and competition is increasingly determined by quality rather than the volume of supply. The emergence of the Prime category, coupled with limited new construction in Classes A and B in the coming years, is expected to intensify competition in the upper market segment, according to analysts. Another factor is the significant share of BTS properties in the overall stock. This indicates that a portion of large companies now prefer to build their own offices rather than rent them, which could further shift the balance between renting and self-construction in the future.
Source: Gazeta.uz
Read the CMWP Uzbekistan review in detail: https://cmwp.uz/iq